Payday Advance Borrow Money

Screenshots
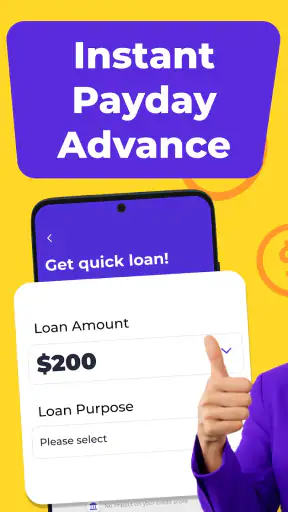
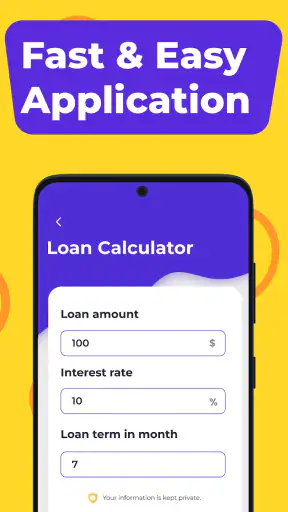
Details
- Rating
- 194.00 reviews
- Version
- 1.2.1
- Developer
- Shpuryk Sergii
Analysis by Norviv
Payday Advance Borrow Money is a finance app built around one focused task: helping people look for a suitable payday cash advance. I found it most useful as a quick starting point when an unexpected bill creates a short gap before the next paycheck. It is free to install, aimed at everyone, and developed by Shpuryk Sergii, but its convenience should not be confused with cheap borrowing. My overall view is simple: it can make loan searching more organized, but it should be treated as a comparison and discovery tool rather than an automatic solution to money problems.
The app has earned a 4.7 average from around 3.2 thousand ratings, with more than 100 thousand installs. Those figures suggest that the basic idea is easy for many people to understand. Still, a positive store score cannot tell you whether a particular advance will be affordable for your situation. The important question is not only whether the app helps you find an offer, but whether you can repay that offer without creating another shortfall.
What using Payday Advance Borrow Money feels like
The experience is best understood as a first step in searching for short-term borrowing. Instead of beginning with a general banking app or searching the web through unrelated pages, I can approach the problem with a specific purpose: find a payday advance that may fit my immediate need. That focus is the app’s clearest strength. When someone is stressed about a due date, a narrow workflow is easier to follow than a broad personal-finance dashboard filled with budgeting tools they did not open the app to use.
The store summary describes an instant cash advance search, but I would keep expectations grounded. “Instant” describes the intended speed of the search process, not a guarantee that money will arrive immediately. A lender still decides whether an application is accepted, and the final terms depend on the lender and the borrower. I would never read the app’s presence on my phone as approval, and I would not plan a bill payment until the funds were actually available.
That distinction is especially important for first-time borrowers. A payday advance may appear convenient because it addresses a small, urgent gap, yet repayment can arrive quickly and leave little room for another surprise. Before using the app, I would write down the amount needed, the date the money must be available, and the exact date and amount I expect to repay. If the repayment would require borrowing again, the app is not solving the underlying problem.
A practical way to search without rushing
My recommended workflow is deliberately slow even though the app is designed for a fast need. First, I would decide whether the expense is genuinely urgent or whether it can be delayed, reduced, or handled through a less expensive option. Then I would use the app to explore the advance search, recording the important terms rather than relying on memory. Finally, I would compare the total repayment with alternatives before submitting anything.
This approach turns the app into a screening tool instead of a button to press under pressure. A useful note should include the amount received, the total amount repaid, the repayment date, any stated fees, and what happens if repayment is late. If an offer does not make those points clear, I would stop and look for a clearer source. The app may help me locate a possibility, but I still have to judge whether it is responsible.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
One non-obvious advantage of this workflow is that it separates discovery from commitment. Many people make expensive decisions because they treat the first available option as the only option. By using Payday Advance Borrow Money to begin the search and then checking the details independently, I have a better chance of noticing an unsuitable repayment schedule. That extra pause is more valuable than shaving a few minutes from the application process.
Where it fits beside familiar alternatives
Compared with a traditional bank app, this finance tool is more narrowly focused on payday advances and less suited to managing everyday money. A bank may be preferable if I have access to an overdraft, a personal loan, or a credit option with a lower overall cost. A credit union may also be worth checking, especially when its repayment structure is easier to understand. For a very small emergency, asking a trusted person, negotiating a bill extension, or using an existing emergency fund can be less expensive than short-term borrowing.
Compared with a web search, the app offers a more direct starting point. A general search can produce confusing results, repeated advertisements, or pages that mix educational material with applications. The focused purpose here can reduce that clutter. The trade-off is that a specialized loan-search experience may encourage me to think about borrowing before I have considered non-borrowing options. I would therefore use the app after a quick affordability check, not before one.
It also differs from budgeting apps. A budgeting app helps me understand recurring income and spending, while this one addresses an immediate borrowing need. If my financial difficulty happens every month, Payday Advance Borrow Money is the wrong long-term instrument. It may help with one isolated emergency, but repeated use points toward a budget problem, unstable income, or bills that need renegotiation. In that situation, a debt counselor, bank adviser, or structured budgeting method would be more useful.
The strongest reasons to consider it
The first strength is focus. The app does not present itself as a complete financial life manager; it centers on finding a payday cash advance. That narrow purpose can be helpful when I already know what kind of information I need and want to avoid wandering through unrelated services.
The second strength is accessibility. It is free, carries an Everyone content rating, and supports devices running Android 5.0 or later. That makes it approachable for people using older Android hardware. The current version is 1.2.1, so I would still check that my device can run it smoothly and that the app behaves as expected after installation, particularly if the phone has limited storage or an older system.
The third strength is the opportunity to compare before committing. Even when an app does not replace careful financial judgment, a dedicated search can help me recognize that short-term advances are not interchangeable. The most useful habit is to treat every result as an invitation to inspect terms, not as a recommendation that automatically suits me.
There is also a psychological benefit to having a defined process. Financial emergencies often produce hurried decisions. A simple sequence—identify the amount, review possible advances, check repayment, and decide—can reduce impulsive behavior. That is not a hidden promise of the app; it is a way I would choose to use its focused design.
The limitation that matters most
The central weakness is built into the category itself: finding a payday advance does not make the borrowing affordable. Short-term loans can be costly, and the repayment deadline may arrive before a borrower’s finances have recovered. The app can help me look for an option, but it cannot remove the risk of fees, a difficult repayment schedule, or a cycle of repeated borrowing.
I would also be cautious about assuming that every result has the same standards or terms. A search experience can bring possibilities together, but I still need to read the final agreement and understand who is actually providing the money. Before entering personal or financial details, I would confirm that I am dealing with the intended lender, review the privacy information, and avoid continuing if the process feels unclear or overly pressuring.
Another point of friction is that speed can reduce reflection. The phrase “cash advance” naturally appeals to someone who needs money now, yet urgency is exactly when careful comparison is most important. I would not use this app while distracted, on a crowded commute, or with a bill collector waiting on the phone. I would set aside enough time to read every amount and date shown before moving forward.
For borrowers who need a larger amount or a longer repayment period, the app may also be a poor fit. A payday advance is designed around a short-term gap, not a major purchase, ongoing rent shortfall, or long-running debt. In those cases, a structured personal loan, creditor negotiation, assistance program, or professional advice may offer a more realistic path. The app’s narrow focus is useful only when the problem is equally narrow and repayment is genuinely manageable.
Everyday situations where it can help
Imagine that a necessary car repair is due just before payday and the vehicle is essential for getting to work. I could use the app to investigate whether a small advance is available, but I would first ask the repair shop about a payment arrangement and check whether my bank offers a less expensive option. If I still considered borrowing, I would compare the total repayment with the repair cost and verify that the next paycheck could cover both the advance and regular essentials.
Another reasonable use is researching options before an emergency becomes critical. If I know that a recurring payment is likely to fall a few days before income arrives, I can review alternatives in advance rather than applying in a panic. This gives me time to question unclear terms and choose not to borrow if the cost is too high. The app is more valuable in that calm preparation stage than as a last-second reaction.
There are situations where I would skip it entirely. If I am already behind on several payments, if I need to borrow to repay another advance, or if my income date is uncertain, taking on a new short-term obligation could make the situation worse. I would also avoid it for discretionary spending. A payday advance for a nonessential purchase is difficult to justify because the item remains after the repayment pressure arrives.
Who should use it and who should look elsewhere
I see the best audience as an Android user facing a specific, temporary cash gap who wants a focused place to begin researching payday advances. That person should have a clear repayment source, enough time to inspect the terms, and the discipline to compare the advance with non-loan alternatives. For that audience, the app’s free access and narrow purpose make it a practical starting point.
It is less suitable for someone looking for financial education, expense tracking, savings goals, credit monitoring, or long-term debt management. Those needs call for different tools. It is also not a good match for anyone who expects the app itself to guarantee approval, guarantee instant funds, or determine which loan is safest without personal judgment. No search interface can make an unaffordable obligation responsible.
Parents and guardians should also remember that an Everyone age label describes the app’s content classification, not a recommendation that every person should borrow. A young or inexperienced user may understand how to search but still underestimate repayment risk. I would encourage anyone unfamiliar with loan terminology to ask a financially trusted adult or adviser to review the terms before proceeding.
My verdict after weighing convenience against cost
Payday Advance Borrow Money is a focused finance app with a clear practical role: it can help me begin looking for a short-term cash advance when an urgent expense cannot wait. Its free availability, accessible Android requirements, and straightforward purpose are meaningful advantages. The strong user response, including a 4.7 average and more than 100 thousand installs, also shows that the concept has found an audience.
My recommendation comes with a firm condition. I would use it to gather and compare possibilities, never as proof that borrowing is affordable. I would check the total repayment, confirm the due date, consider a bank or credit-union alternative, and look for bill negotiation or personal support before accepting an advance. If repayment depends on another loan, I would walk away.
For a one-time emergency with a dependable incoming payment, the app may save time and bring structure to a stressful search. For recurring shortages, existing debt, uncertain income, or a large financial need, a different solution is better. In the end, the app is useful when it helps me make a more informed decision—and harmful only when its speed encourages me to skip the decision-making part.
Frequently Asked Questions
01What is Payday Advance Borrow Money, and how does it work?
Payday Advance Borrow Money is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account, you typically provide personal, employment, income, and banking information so the service can assess eligibility. If approved, the requested amount may be transferred to your bank account, subject to the provider’s terms, fees, and processing times.
02Who can use Payday Advance Borrow Money, and what requirements apply?
Eligibility depends on the provider and may vary by location. In general, applicants may need to be adults with a valid government-issued identification document, an active bank account, a regular source of income, and a working phone number or email address. The app may also review banking details and repayment history. Approval is not guaranteed, even when basic requirements are met.
03How much does borrowing through the app cost?
Before accepting an advance, carefully review the complete cost shown in the app, including interest, service charges, subscription fees, origination fees, late-payment charges, and any optional services. The annual percentage rate can be significantly higher than traditional personal loans because payday advances are short-term products. Always compare the total repayment amount with the money you receive.
04When will I receive the money, and how is repayment handled?
Funding speed depends on approval time, bank processing, weekends, holidays, and the transfer method selected. Some users may receive funds quickly, while others may wait longer. Repayment is commonly scheduled for a future payday and may be collected automatically from a linked bank account or debit card. Confirm the exact due date and payment method before accepting the advance.
05Is Payday Advance Borrow Money safe to use?
Use the app only after checking its privacy policy, developer information, permissions, customer support options, and legal availability in your region. Never provide banking credentials through unofficial links or download modified versions from unknown websites. Read the loan agreement carefully, especially the total repayment amount and data-sharing terms. If repayment could strain your budget, consider lower-cost alternatives first.


